50-30-20 Budget Rule Explained: A 2026 Guide for Beginners
Managing personal finances in 2026 can feel like navigating a complex maze. Between economic shifts, evolving subscription models, dynamic housing markets, and changing lifestyle costs, staying in control of your money requires a simple, reliable framework. Enter the 50 30 20 budget rule—one of the most effective, straightforward money management strategies ever designed, brought to you by WisdomLand.in.
Popularized by Senator Elizabeth Warren in her book All Your Worth: The Ultimate Lifetime Money Plan, the 50 30 20 budget rule offers an intuitive blueprint for managing your income without requiring tedious spreadsheet tracking for every single cent. Learn more about budgeting basics from the Consumer Financial Protection Bureau (CFPB). By dividing your income into three core buckets, you can eliminate financial stress and build lasting wealth.
In this comprehensive 2026 beginner’s guide, you will learn exactly how the 50 30 20 budget rule works, how to calculate your personalized spending buckets, real-world examples, actionable implementation steps, common mistakes to avoid, and answers to frequently asked questions.
What is the 50 30 20 Budget Rule?
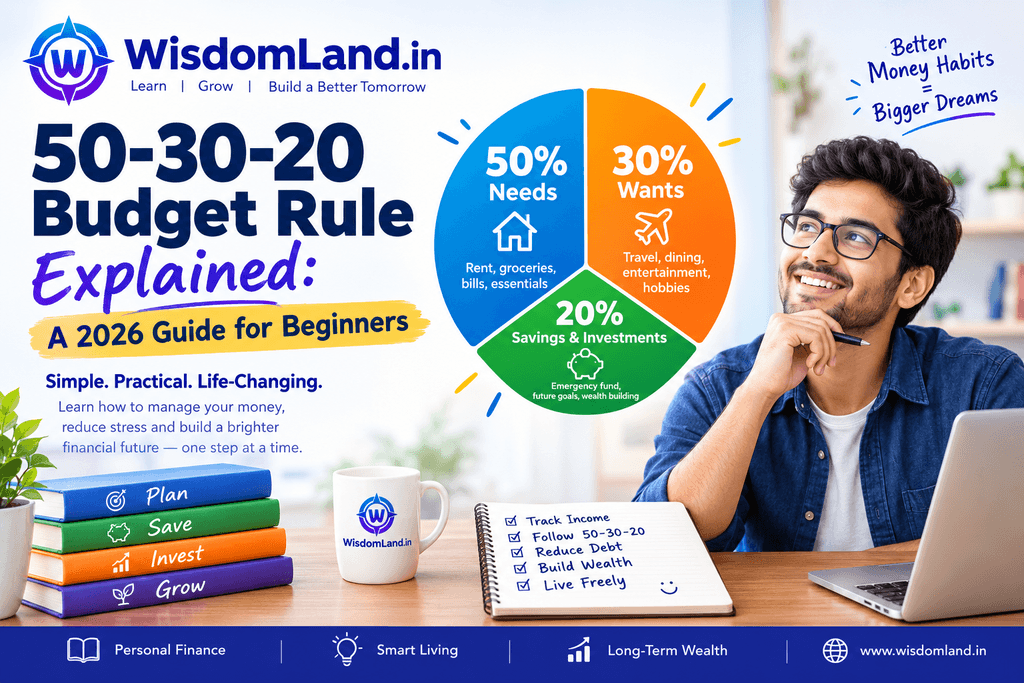
The 50 30 20 budget rule is a proportional budgeting method that divides your monthly after-tax income (net income) into three distinct categories:
- 50% for Needs: Essential living expenses required for basic survival and daily operations.
- 30% for Wants: Lifestyle choices, entertainment, and non-essential personal desires.
- 20% for Savings and Debt Payoff: Wealth building, emergency preparation, and long-term financial security.
Instead of tracking every single coffee purchase or grocery item individually, the 50 30 20 budget rule groups your spending into macro-categories. This high-level view grants financial flexibility while guaranteeing that long-term savings goals are met consistently. It serves as a foundational component of modern personal finance tips for beginners.
Calculating Net Income vs. Gross Income
Before applying the percentage breakdown, you must determine your Net After-Tax Income. This is the actual amount of money that enters your bank account.
- W2 / Salaried Employees: Your net income is your actual take-home pay on your paycheck after federal, state, and local taxes, as well as automatic deductions for healthcare premiums or employer retirement matches.
- Self-Employed / Freelancers: Your net income is your gross business revenue minus business expenses and estimated quarterly tax liabilities.
Understanding this distinction is crucial when learning how to budget salary in 2026, as budgeting based on gross income will lead to overspending in every category.
The Core Breakdown: Needs, Wants, and Savings
To successfully execute the 50 30 20 budget rule, you must clearly understand what fits into each category. The following needs wants savings breakdown provides exact guidelines.
1. 50% of Your Income: Needs (Essential Expenses)
Needs are obligations that you simply cannot avoid without experiencing severe consequences. If you were to lose your job tomorrow, these are the critical bills you would still have to pay to maintain physical safety, health, and legal compliance.
Key examples of Needs include:
- Housing: Rent payments, mortgage principal/interest, property taxes, and mandatory home insurance.
- Utilities: Electricity, water, natural gas, trash collection, and basic home internet connection.
- Groceries: Essential dietary foods and core household cleaning supplies (excluding dining out, alcohol, and luxury food items).
- Transportation: Automobile loan payments, auto insurance premiums, fuel, public transit passes, and essential vehicle maintenance.
- Healthcare: Health insurance premiums, required prescription medications, copays, and necessary medical visits.
- Minimum Debt Payments: The legal minimum required monthly payments on credit cards, student loans, or personal loans.
2026 Inflation Reality Check: In many high-cost-of-living (HCOL) urban areas, housing costs alone can consume 40% or more of net income. If your Needs exceed 50%, don’t panic. You can temporarily adjust the ratio (e.g., 60/20/20) while working to optimize fixed costs over time.
2. 30% of Your Income: Wants (Lifestyle Choices)
Wants are all the extra things that make life enjoyable but are not essential for basic survival or employment. This category allows you to spend money guilt-free on your passions and hobbies without feeling constrained or deprived.
Key examples of Wants include:
- Dining Out & Takeout: Restaurant meals, daily coffee shop visits, bar tabs, and food delivery apps.
- Entertainment: Movie tickets, concert passes, sporting event seats, and gaming purchases.
- Subscriptions: Streaming video services (Netflix, Hulu), music platforms (Spotify), app subscriptions, and digital news services.
- Travel & Vacations: Flights, hotels, weekend getaways, and leisure travel activities.
- Shopping: Non-essential clothing, high-end electronics, home decor, and personal luxury items.
- Fitness & Hobbies: Gym memberships, boutique workout classes, golf memberships, and craft supplies.
Differentiating Needs from Wants: Ask yourself, “Can I survive and maintain my employment without this service for 3 months?” For example, basic internet access is a Need for remote work, but upgraded 1-Gigabit fiber speed with premium channel add-ons is a Want.
3. 20% of Your Income: Savings & Debt Payoff (Financial Goals)
The final 20% of your income is dedicated to securing your future and building long-term wealth. This is the cornerstone of financial independence and forms the baseline of any structured monthly budget plan.
Key examples of Savings and Debt Payoff include:
- Emergency Fund: Building 3 to 6 months of living expenses in a high-yield savings account (HYSA).
- Retirement Contributions: Individual Retirement Accounts (Traditional or Roth IRA), 401(k) contributions beyond company match, or pension plan additions. Explore retirement options on Investor.gov.
- Investments: Automated index fund investing, Systematic Investment Plans (SIPs), brokerage accounts, and real estate funds.
- Extra Debt Payoff: Accelerated debt payments above the legal minimum requirement to eliminate high-interest credit card debt or personal loans quickly.
- Short-Term Savings Goals: Down payments for a home, wedding funds, or a new vehicle cash pool.
Step-by-Step Guide: How to Implement the 50 30 20 Budget Rule in 2026
Implementing the 50 30 20 budget rule in 2026 is simple when broken down into six structured, actionable steps.
Step 1: Calculate Your Total Take-Home Income
Examine your monthly pay stubs, direct deposits, or invoice earnings. Sum all sources of steady income to determine your net monthly take-home pay.
Step 2: Audit Your Past 30 to 90 Days of Expenses
Review your bank statements, credit card bills, and digital payment app histories from the past 1 to 3 months. Categorize every transaction into Needs, Wants, or Savings/Debt.
Step 3: Calculate Your Target Category Limits
Multiply your net monthly income by 0.50, 0.30, and 0.20 to reveal your exact monthly spending caps for each bucket.
Step 4: Compare Actual Spending Against Targets
Compare your historical spending numbers against your new target limits. Identify areas where your current lifestyle exceeds the baseline target percentages.
Step 5: Make Strategic Adjustments
If your Wants exceed 30%, audit unused subscriptions or trim restaurant dining. If your Needs exceed 50%, look for opportunities to lower variable utility costs, shop for better auto insurance rates, or evaluate housing options when your lease renews.
Step 6: Automate Your Finances
Set up automatic bank transfers on payday. Transfer 20% directly into savings and investment accounts first (“pay yourself first”) so you are never tempted to spend money intended for your future.
Real-World 50 30 20 Budget Rule Examples for 2026
Let’s examine how the 50 30 20 budget rule translates into exact dollar figures across common monthly income tiers in 2026. Reviewing a concrete 50 30 20 rule example helps clarify how the math works in daily life.
Example 1: Entry-Level Income ($3,000 / Month Net)
- Needs (50% = $1,500): $1,000 Rent/Utilities share, $300 Groceries, $150 Car Insurance/Gas, $50 Minimum Student Loan payment.
- Wants (30% = $900): $300 Dining & Drinks, $150 Shopping, $100 Subscriptions & Mobile Plan, $200 Travel Fund, $150 Hobbies.
- Savings (20% = $600): $300 High-Yield Savings Account (Emergency Fund), $200 Roth IRA, $100 Accelerated Loan Payoff.
Example 2: Mid-Level Professional ($5,000 / Month Net)
- Needs (50% = $2,500): $1,700 Housing/Mortgage, $400 Groceries, $250 Utilities & Transport, $150 Insurance.
- Wants (30% = $1,500): $500 Dining Out, $300 Travel & Leisure, $200 Shopping, $250 Entertainment, $250 Gym & Personal Care.
- Savings (20% = $1,000): $500 Retirement Investments, $300 HYSA Emergency Fund, $200 House Down Payment Fund.
Income Distribution Comparison Table
The following matrix illustrates how monthly take-home income maps directly across the three core categories and projects annual wealth accumulation under this framework:
| Monthly Net Income | Needs (50%) | Wants (30%) | Savings & Debt (20%) | Annual Total Saved |
|---|---|---|---|---|
| $2,500 / month | $1,250 | $750 | $500 | $6,000 / year |
| $3,500 / month | $1,750 | $1,050 | $700 | $8,400 / year |
| $5,000 / month | $2,500 | $1,500 | $1,000 | $12,000 / year |
| $7,500 / month | $3,750 | $2,250 | $1,500 | $18,000 / year |
| $10,000 / month | $5,000 | $3,000 | $2,000 | $24,000 / year |
What to Do If Your Expenses Don’t Fit the 50 30 20 Rule?
The 50 30 20 budget rule is a flexible guideline, not an unyielding law. Depending on your current life stage, family size, and geographical location, alternative ratios may be necessary:
- High Cost of Living (HCOL) Adjustments (60 / 20 / 20): If local rent or housing costs consume a large portion of your pay, reduce your Wants to 20% while keeping Savings firm at 20% to safeguard your financial future.
- Aggressive Debt Elimination (50 / 10 / 40): If carrying high-interest credit card debt, temporarily trim Wants to 10% and allocate 40% toward rapid debt cancellation and emergency reserves.
- High Earner / FIRE Acceleration (30 / 20 / 50): As your salary expands, keep fixed needs stable and direct 50% or more toward financial independence and early retirement goals.
Pros and Cons of the 50 30 20 Budget Rule
Advantages
- Extreme Simplicity: Eliminates the frustration of tracking dozens of individual micro-budget categories.
- Guarantees Wealth Building: Prioritizes financial goals by securing 20% of your income upfront.
- Guilt-Free Spending: Allocates 30% of income for personal enjoyment without financial stress or guilt.
- High Adaptability: Easily adjusts whenever your income increases, decreases, or stabilizes.
Disadvantages
- HCOL Challenges: Can be difficult for lower-income earners or residents in high-rent metro areas where baseline needs exceed 50%.
- Vague Boundaries: The line between Needs and Wants can blur without consistent personal discipline.
- Not Aggressive Enough for FIRE: Investors pursuing early retirement may find a 20% savings rate too conservative.
Common Budgeting Mistakes to Avoid in 2026
- Categorizing Wants as Needs: Labeling organic gourmet food, premium boutique fitness classes, or expensive smartphone upgrades as essential living expenses.
- Forgetting Irregular Expenses: Failing to factor in annual insurance premiums, property taxes, vehicle registrations, or seasonal holiday spending.
- Neglecting Automation: Attempting to save whatever is “left over” at the end of the month manually instead of automating transfers on payday.
- Ignoring Interest Rates: Paying down low-interest fixed debt (2-3%) aggressively while ignoring high-interest credit cards (20%+).
Frequently Asked Questions (FAQs)
Q1: Is the 50 30 20 budget rule based on gross or net income?
The 50 30 20 budget rule is strictly calculated using your net after-tax income (your actual take-home pay deposited directly into your bank account).
Q2: Does debt repayment go into Needs or Savings?
Minimum required debt payments belong in the Needs (50%) category because failing to pay them damages your credit score and incurs legal penalties. Any extra, accelerated debt payments above the minimum belong in the Savings & Debt (20%) category.
Q3: Is 20% savings enough to retire comfortably?
Saving 20% of your net income starting in your 20s or early 30s is generally sufficient to achieve a comfortable, financially secure retirement by standard age thresholds due to long-term compound growth.
Q4: How do freelancers implement the 50 30 20 rule with irregular income?
Freelancers should calculate their baseline budget using their lowest average monthly income from the previous year. Alternatively, establish a separate business buffer fund to pay yourself a predictable monthly salary.
Conclusion: Take Control of Your Financial Future in 2026
The 50 30 20 budget rule remains one of the simplest, most effective tools for building wealth and achieving peace of mind. By taking a macro view of your finances—allocating 50% to needs, 30% to wants, and 20% to savings—you cultivate long-term financial discipline without stripping the everyday joy out of life.
Start today: audit your spending from the past 30 days, calculate your personal category limits, set up automated savings transfers, and take total control of your financial journey in 2026 with more resources at WisdomLand.in!